
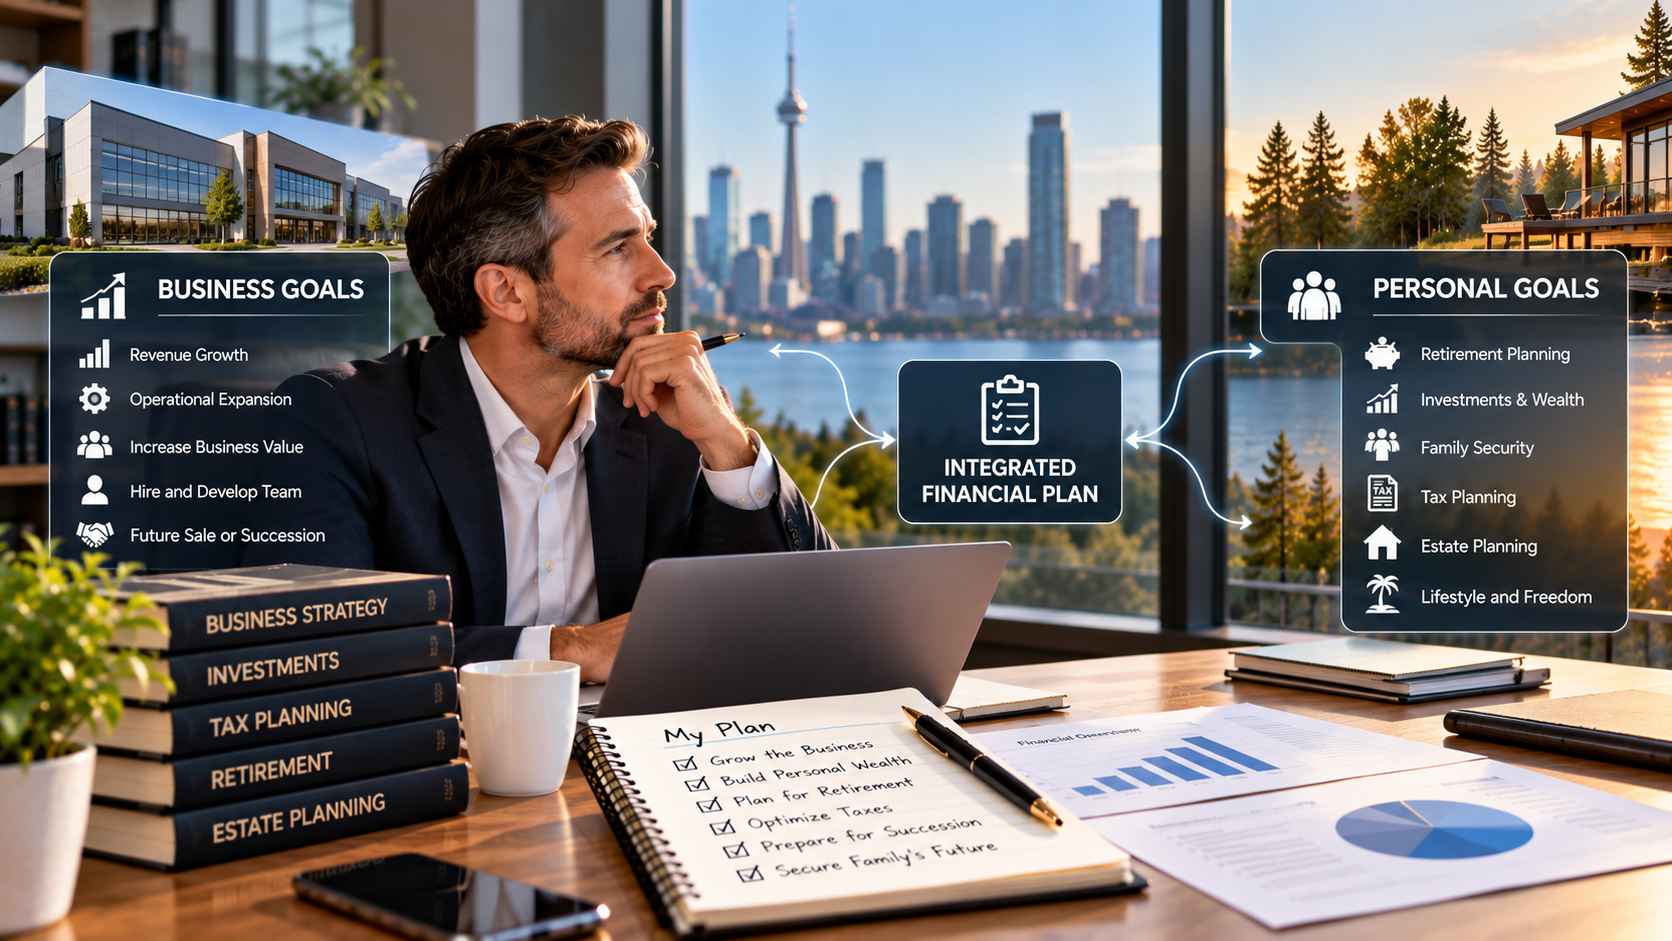
For many entrepreneurs, the business is both a career and one of the most valuable assets they own. Revenue supports the household, profits can be reinvested into growth, and the eventual value of the company may form an important part of the owner’s long-term financial plans.
That connection can also create a planning gap.
A decision that makes sense for the business may not always align with the owner’s personal financial objectives. Reinvesting heavily in the company, for example, may support expansion while leaving less wealth outside the business. Similarly, preparing for a future sale without considering retirement income, taxes, estate planning, or family goals can leave important questions unanswered.
A financial plan that considers both sides can help business owners understand how today’s decisions may affect their personal financial future.
Business Growth and Personal Wealth Are Connected
Business owners often measure success through revenue, profitability, growth, market position, or the value of the company.
Those measures are important, but they do not tell the entire personal financial story.
An owner may have a profitable business while holding relatively little wealth outside the company. Another may have significant personal investments but still depend heavily on business income to maintain their lifestyle.
The distinction matters because business wealth is not necessarily the same as personal financial security.
A business may require ongoing investment in employees, equipment, property, technology, inventory, or working capital. The owner may also need to retain cash within the company for future opportunities.
At the same time, personal goals continue to exist.
Exponent Investment Management works with professionals, business owners, and families on wealth management and financial planning, illustrating how business and personal financial considerations can be brought into the same broader planning conversation.
The objective is not to treat the business as separate from personal finances. It is to understand how the two interact.
Understand Where Your Wealth Actually Sits
One of the first questions business owners can ask is where most of their wealth is concentrated.
If a large portion of net worth is represented by shares in one company, the owner’s financial future may be closely tied to that company’s performance and eventual transition.
That concentration can be reasonable during the growth phase of a business. Building a company often requires capital, time, and risk. However, the balance can become more important as an owner approaches retirement or begins thinking about succession.
Building personal assets outside the company can provide another source of flexibility.
This does not mean there is a single appropriate level of diversification for every entrepreneur. Personal circumstances, investment objectives, liquidity requirements, and risk tolerance all matter.
The more important point is to recognize concentration rather than allowing it to develop without consideration.
Plan for Retirement Before You Need It
A business owner may assume that the eventual sale of the company will provide the funds needed for retirement.
That may become part of the plan, but relying entirely on a future transaction can introduce uncertainty.
The timing of a sale may change. The owner may decide to transfer the company to family members or employees rather than sell it outright. The business could also be worth more or less than expected when the owner is ready to leave.
Retirement planning can therefore begin by considering the lifestyle the owner wants after leaving the business.
Housing, travel, healthcare, family support, debt, hobbies, and other expenses all influence the amount of income required. Retirement may also happen gradually, with an owner reducing their involvement rather than stopping work completely.
The Government of Canada’s retirement resources encourage Canadians to consider retirement timing, spending needs, and different sources of retirement income when planning for the future.
For entrepreneurs, the exercise can be especially useful because business income, personal investments, pensions, government benefits, and potential business proceeds may all form part of the eventual retirement picture.
Consider Taxes and Estate Planning
Business and personal financial planning can become more complicated when tax considerations enter the picture.
The way money moves between a company and its owner, how investments are structured, and how a future business transition is organized can all have financial implications.
This is why tax planning should generally be considered alongside broader financial decisions rather than treated as an issue to address only when a transaction is already underway.
Estate planning is similarly important.
For an owner whose company represents a substantial part of family wealth, an estate plan may need to address business interests as well as personal assets.
Questions can include who should receive ownership interests, who can make financial decisions if the owner becomes unable to do so, and how the business should be handled after death.
The specific legal and tax considerations vary by situation, so business owners should involve qualified legal and tax professionals where appropriate.
Prepare for Succession or a Future Sale
Succession planning is not only about identifying who will eventually run the company. It is also about understanding what the transition means for the owner’s personal finances.
An owner might sell to another entrepreneur, transfer ownership to family, sell to employees or partners, or gradually reduce their involvement while maintaining an ownership interest.
Each path can create a different financial outcome.
The Government of Canada has identified business succession planning and business transfers as important areas for Canadian entrepreneurs and small-business owners preparing for ownership transitions. Government of Canada business succession planning guidance
This makes early planning valuable. An owner does not need to know exactly which exit strategy will eventually be chosen, but considering several possibilities can reveal financial gaps before a transition becomes urgent.
For example, a family transfer may produce a different level or timing of personal liquidity than an external sale. Remaining involved after a transaction may also create a different income picture from a complete exit.
Review the Plan as the Business Changes
A financial plan should evolve as the business and the owner’s life change.
A company that begins as a small operation may eventually acquire property, hire employees, expand into new markets, or develop significant retained value. At the same time, the owner’s personal circumstances may change through marriage, children, real estate purchases, inheritance, career changes, or evolving retirement goals.
Those changes can affect one another.
A new business opportunity might require additional capital but also increase concentration. A decision to purchase commercial property might affect liquidity. A planned retirement date might influence how much wealth should remain tied to the company.
Regular reviews can help identify these connections rather than allowing individual decisions to develop independently.
Bring Business and Personal Planning Together
The value of integrated planning is often found in the connections between decisions.
An owner may be thinking about increasing business investment, while also wondering whether enough personal wealth is being built outside the company. Another may be considering succession while trying to determine how retirement income will be generated.
Financial planning for business owners can provide a framework for considering these questions together, while accountants, tax professionals, lawyers, and other specialists can contribute expertise where their specific knowledge is required.
This does not mean every decision needs to be complicated. It means the owner can understand how one decision may affect another before committing to a course of action.
The goal is not to predict investment returns, guarantee a business valuation, or assume that a particular exit will happen. It is to create a flexible financial framework that can adapt as circumstances change.
Build a Financial Plan Around the Whole Picture
A successful business can create substantial opportunities, but the company’s success should be viewed as one part of the owner’s broader financial life.
Business income, personal investments, retirement planning, taxes, estate planning, and succession are connected in ways that can become more important as the company grows.
By considering these areas together, business owners can identify where their financial future is concentrated, understand what they may need beyond the business, and prepare for different paths forward.
The most useful plan is not necessarily the most complicated one. It is one that reflects the owner’s goals, recognizes the relationship between business and personal wealth, and can be reviewed as both the company and the owner’s priorities evolve.